IFPA shieldINSTITUTE OF
FINANCIAL
PROFESSIONALS
AUSTRALIA
News

Message from the Head of Technical Services - Treasurer announces major changes to Division 296 tax

· Keri-Ann · Updated 24 September 2026


Message from the Head of Technical Services - Treasurer announces major changes to Division 296 tax

Dear Member, Today’s announcement from the Treasurer marks a significant shift in the proposed Division 296 tax and a welcome improvement from the original design. From the beginning, the Institute of Financial Professionals Australia (IFPA) has strongly opposed this measure…

Dear Member,

Today’s announcement from the Treasurer marks a significant shift in the proposed Division 296 tax and a welcome improvement from the original design.

From the beginning, the Institute of Financial Professionals Australia (IFPA) has strongly opposed this measure, raising serious concerns about fairness, complexity, and the long-term sustainability of the superannuation system. We have consistently advocated that Division 296, in its original form, should not proceed.

Importantly, we want to thank our members and their clients who took action by using the Division 296 Tax Advocacy Kit we shared earlier this year. Many of you reached out to your local MPs and other key decision-makers to express your concerns and share the profession’s perspective. Your efforts have played a vital role in shaping this outcome and amplifying our collective voice.

Through this united advocacy – from members engaging directly with policymakers to IFPA’s ongoing work with government and Treasury – we’ve achieved meaningful improvements to the proposed tax. The result is a fairer and more practical framework for both professionals and the broader community, demonstrating the strength of our profession when we act together.

What’s changing

The government has announced several key adjustments to the proposed Division 296 tax:

  • The tax will only apply to future actual earnings, not unrealised gains as originally proposed.
  • The $3 million threshold will be indexed to the consumer price index (CPI) in $150,000 increments, keeping pace with the transfer balance cap (TBC).
  • A new second threshold of $10 million will be introduced, with earnings above this level taxed at 40%. This will also be CPI-indexed in $500,000 increments.
  • The start date will be delayed by one year to 1 July 2026, based on members’ total super balance (TSB) as at 30 June 2027, with first assessments expected in 2027-28.
  • The tax will apply to defined benefit pensions, ensuring consistent treatment across super structures.

In summary, the effective cumulative tax rates within super will be:

  • 15% on earnings for TSBs up to $3 million.
  • 30% on a portion of earnings for TSBs between $3 million and $10 million (ie, standard 15% tax rate + an extra 15% tax on earnings attributable to balances over $3 million).
  • 40% on earnings attributable to balances exceeding $10 million (ie, 15% + 15% + 10%).


How the ATO will administer it

Super funds will continue reporting members’ balances to the ATO, which will calculate each individual’s TSB.

For members exceeding the relevant thresholds, the ATO will:

  1. Request the fund’s calculation of realised earnings for that member.
  2. Use this data to calculate and issue the tax liability.

Funds will attribute an appropriate share of realised earnings to affected members based on taxable income concepts, adjusted for elements such as contributions and pension income, using existing reporting systems and ATO guidance to ensure fairness.


Calculating super earnings

The ATO’s method for calculating the tax liability will be settled during consultation but it is anticipated that it will follow these five broad steps:

1. ATO notifies the super fund that there is an in-scope member
(ie, a member with a TSB of $3 million or more)

2. Fund calculates realised earnings attributable to that in-scope member and reports this to ATO

Note: the trustee of the super fund could attribute earnings to in-scope members using existing processes or on a fair and reasonable basis (as supported by ATO guidance). 

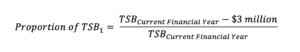
3. ATO calculates the proportion of the TSB exceeding the $3 million threshold:

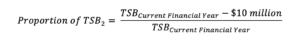
4. ATO calculates the proportion of the TSB exceeding the $10 million threshold (if applicable):

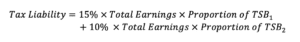
5. ATO calculates the total Div 296 tax liability for all that member’s interests:

This approach results in an additional 15% tax on a proportion of earnings between $3 – 10 million and an additional 25% tax on a proportion of earnings over $10 million. This is in addition to the standard 15% fund tax rate on income.


Examples

Megan – both APRA-regulated fund and SMSF interests

Megan (58) has a TSB of $4.5 million split across an APRA fund ($2.3 million) and an SMSF ($2.2 million).Her total realised earnings for 2026–27 are $300,000.

The proportion of her $4.5 million TSB above the $3 million threshold is 33.33%.

Her additional Division 296 tax is $15,000 (0.15 x $300,000 x 0.3333).


Emma – SMSF member with over $10 million

Emma (55) has a TSB of $12.9 million and $840,000 in realised earnings at the end of 2026-27.

The proportion of her balance above the $3 million threshold is 76.74% and the proportion of her balance above the $10 million threshold is 22.48%.

Her total Division 296 tax is $115,581 [(0.15 x $840,000 x 0.7674) + (0.10 x $840,000 x 0.2248)]. Note the combined tax rate on earnings over $10 million is 25%.

Next steps

The government will introduce legislation to implement these changes ahead of the 1 July 2026 start date, following further consultation with industry.

IFPA will continue to advocate strongly on behalf of members and engage closely with Treasury throughout the consultation period.

We invite members to share feedback or raise any concerns by contacting us at: [email protected]. Your insights help us shape a fairer and more effective superannuation system.

Warm regards,
Natasha Panagis
Head of Technical Services
The Institute of Financial Professionals Australia


© Institute of Financial Professionals Australia (IFPA)

Level 14, 330 Collins Street, Melbourne, Victoria, 3000, Australia

(03) 8851 4555 | Privacy Policy

Don't want these emails? Unsubscribe.

Related articles

Weekly Super & Financial Services BulletinSuper Notes

Weekly Bulletin

1 Oct 2026

The news you need to know this week

Read more
Latest Weekly Updates

25 September 2026

25 Sept 2026

21 September 2026 to 24 September 2026 Weekly Bulletin Contents TAX MONDAY 21 SEPTEMBER 2026 TPB guidance on reforms to sanctions powers The Tax Practitioners Board (TPB) has published information about the new sanctions powers that will enable the TPB to respond more effectively to serious…

Read more
Awards

Meet the Management Team

24 Sept 2026

Thursday, 1 October 2026 • The Fullerton Hotel, Sydney Welcome reception: 6:00pm • Official Start: 7:00pm AEDT • Business Attire MEET THE IFPA MANAGEMENT TEAM Meet Dr Heidi Ivory CEO, [email protected] Dr Heidi Ivory is a commercially focused executive with a diverse…

Read more